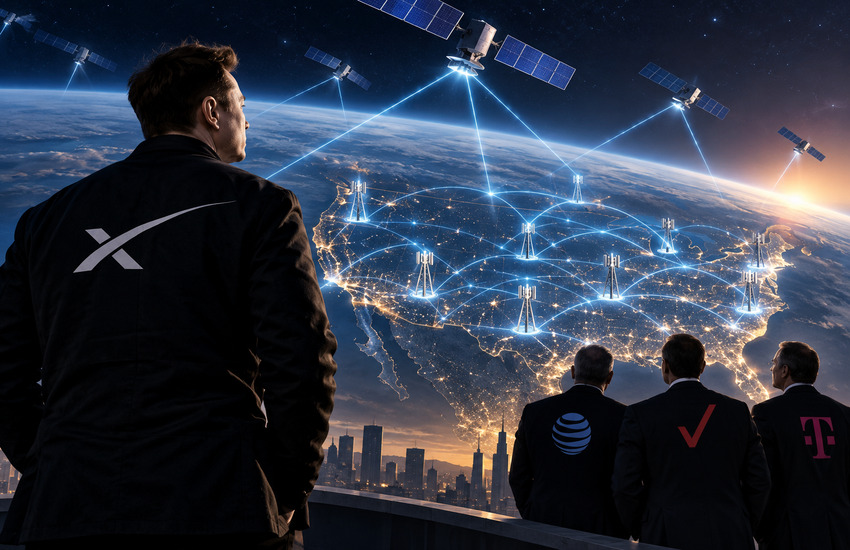
SpaceX (NASDAQ:SPCX) is starting to look like something the U.S. wireless industry has not faced in years: a potential new nationwide competitor. Starlink began as a satellite broadband service, but SpaceX is now pushing much deeper into mobile connectivity. The company has committed $19.6 billion to acquire 65 MHz of spectrum from EchoStar, creating the foundation for a Starlink Wireless Network. The significance became clearer during SpaceX’s Q2 earnings call. President Gwynne Shotwell said the acquired spectrum includes terrestrial components and confirmed that SpaceX intends to build them out. Management also expects next-generation Starlink Mobile satellites to begin launching in 2027, with service starting around the end of that year.
The timing adds another layer. The FCC is scheduled to vote on September 30 on proposals involving more spectrum for space-based wireless services. Meanwhile, SpaceX’s Connectivity business is already producing billions in revenue and EBITDA. The question is no longer whether SpaceX is interested in mobile. It is how far the company intends to take that ambition.
Starlink Wireless Network Is Becoming More Than A Satellite Service
The biggest development came directly from management. Shotwell confirmed that the EchoStar spectrum has terrestrial components. SpaceX intends to build out that terrestrial capability as part of what she described as a true mobile service. That makes the strategy much broader than simply connecting phones to satellites when terrestrial networks disappear.
SpaceX is also considering a different deployment model from traditional carriers. Rather than relying only on large cellular towers, management discussed placing smaller cellular base stations alongside existing Starlink broadband equipment. Musk described a system involving many small stations deployed across homes and businesses. Such a model could allow SpaceX to add capacity where demand requires it instead of replicating every piece of a traditional wireless network.
That matters because satellite connectivity has physical limitations. Dense buildings and indoor environments remain harder to serve directly from orbit. A Starlink Wireless Network that includes both satellite and terrestrial capacity would address a different problem.
There is still a major capital question. During the earnings call, an Evercore ISI analyst estimated that becoming a true fourth U.S. carrier could require well over $100 billion of mobile capital spending over time. That was the analyst’s estimate, not SpaceX guidance. Shotwell declined to provide a CapEx forecast and instead argued that SpaceX’s deployment approach could be more capital efficient.
SpaceX is moving Starlink Mobile toward a hybrid satellite-terrestrial network backed by 65 MHz of acquired spectrum and next-generation satellites. The strategic opportunity is significant, but the investment debate increasingly hinges on whether SpaceX can translate its infrastructure advantages into competitive mobile economics while supporting an exceptionally demanding valuation.
SpaceX has moved its wireless strategy from concept toward a defined infrastructure roadmap. The deciding issue is whether its spectrum, satellite scale, and terrestrial buildout can produce competitive economics quickly enough to support the expectations embedded in its valuation.
Sixty-Five Megahertz Changes The Mobile Capacity Equation
SpaceX’s spectrum position helps explain why management is talking more openly about mobile competition. Starlink Mobile currently operates using roughly 5 MHz of bandwidth through local telecom providers. Through the EchoStar spectrum, SpaceX expects to have 65 MHz available. That represents a substantial increase in the spectrum supporting the service.
Spectrum is only one part of the equation. SpaceX also plans to launch roughly ten times as many next-generation mobile satellites. Shotwell simplified the combination for investors: approximately ten times more spectrum paired with roughly ten times more satellites. Management therefore characterized the future Starlink Mobile system as potentially around 100 times better than the current system.
The timeline is becoming clearer too. SpaceX expects to begin flying its next-generation Starlink Mobile satellites in 2027. Management expects service to start around the end of 2027. The company’s near-term priority is deploying those satellites before integrating the EchoStar spectrum.
That makes the Starlink Wireless Network story more concrete. SpaceX is not merely accumulating spectrum for an undefined future use. It has identified new satellites, substantially greater bandwidth, and a service timetable.
The competitive ambition is also explicit. Shotwell compared Starlink Mobile with AT&T, Verizon, and T-Mobile during the earnings call. She placed their combined annual revenue at roughly $600 billion and said SpaceX expects to compete for some of those customers.
September 30 Adds A New Regulatory Catalyst
The next date investors should watch is September 30. The FCC is scheduled to vote on proposals designed to make more than 1,000 MHz of spectrum available for space-based wireless services. The proposal involves the 12 GHz and 42 GHz bands and is intended to expand the capacity available to satellite connectivity.
This should not be interpreted as SpaceX simply receiving another 1,000 MHz for smartphones. It does not mean that. The larger point is that U.S. spectrum policy is evolving alongside the growth of satellite-based communications. That creates an important regulatory backdrop for companies building networks that increasingly blur the line between terrestrial and space connectivity.
SpaceX already cleared another important regulatory step. Management said the FCC recently approved the transfer of the 65 MHz EchoStar spectrum, which Shotwell described as a foundational competitive advantage for Starlink Mobile.
The September 30 decision therefore comes as SpaceX is moving from regulatory approval toward execution. The company still needs to deploy satellites, integrate spectrum, build terrestrial capacity, and deliver reliable service.
For the Starlink Wireless Network, regulation remains one of the variables that can influence how quickly that process develops. September 30 matters because it offers another signal about how aggressively U.S. regulators will accommodate expanding space-based communications infrastructure.
Starlink Already Has The Scale To Fund The Push
Building a nationwide mobile business requires more than technology. It also requires a financial engine, and this is where SpaceX’s latest results change the discussion.
SpaceX generated $7.8 billion of Q2 revenue, up 92% year over year. Adjusted EBITDA reached $3.5 billion, up 191%, while the quarterly net loss narrowed to $541 million. These are company-wide numbers, but the Connectivity segment provides the clearest view of Starlink’s underlying economics.
Connectivity revenue reached $4.3 billion, rising 66% year over year. Operating income increased 79% to $1.7 billion, while adjusted EBITDA climbed 64% to $2.6 billion. Operating margin expanded by nearly three percentage points. Those figures show that Starlink’s existing connectivity operation is already generating meaningful earnings while SpaceX funds the next stage of expansion.
SpaceX also has substantial liquidity. The company ended Q2 with $100 billion of cash, cash equivalents, and marketable securities, following its IPO and investment-grade debt offering. It reported $47.5 billion of backlog.
The incumbent advantage should still be kept in perspective. AT&T, Verizon, and T-Mobile have established tower networks, spectrum portfolios, device relationships, and dense urban coverage. SpaceX still has to prove that the Starlink Wireless Network can deliver competitive everyday service at scale.
What has changed is SpaceX’s ability to finance that experiment. The company now has the spectrum, liquidity, satellite infrastructure, and an existing connectivity business to pursue it.
Final Thoughts
SpaceX is not America’s fourth major wireless carrier today. But its strategy has become much harder to dismiss as a simple satellite extension. Management has confirmed plans for terrestrial infrastructure, 65 MHz of EchoStar spectrum, next-generation mobile satellites beginning in 2027, and a service target around the end of that year. The proposed Starlink Wireless Network is increasingly taking the shape of an actual operating strategy rather than a distant possibility.
The execution burden remains substantial. SpaceX must integrate the new spectrum, deploy significantly more satellites, build terrestrial capacity, and provide reliable connectivity in environments where established carriers already have dense infrastructure. The September 30 FCC vote adds another regulatory milestone, but it does not remove those operational challenges.
Valuation makes the distinction especially important.
SpaceX has defined the wireless ambition; execution must now justify the valuation.
SpaceX currently trades at approximately 84.64x LTM enterprise value-to-revenue and 87.26x LTM price-to-sales. Its LTM EV/gross profit multiple is approximately 163.17x, while LTM EV/EBITDA stands at roughly 330.76x. LTM EV/EBIT and diluted P/E are negative because the corresponding earnings measures remain negative.
Those are demanding multiples. They indicate that investors are assigning substantial value to growth that has yet to flow fully through current earnings. Starlink Mobile could become one avenue for supporting those expectations, especially if management delivers the capacity gains it has outlined. But the valuation also leaves less room for execution disappointments.
For now, the wireless thesis has moved beyond speculation: SpaceX has outlined what it intends to build, but the economics and competitive impact still have to be demonstrated.
Disclaimer: We do not hold any positions in the above stock(s). Read our full disclaimer here.