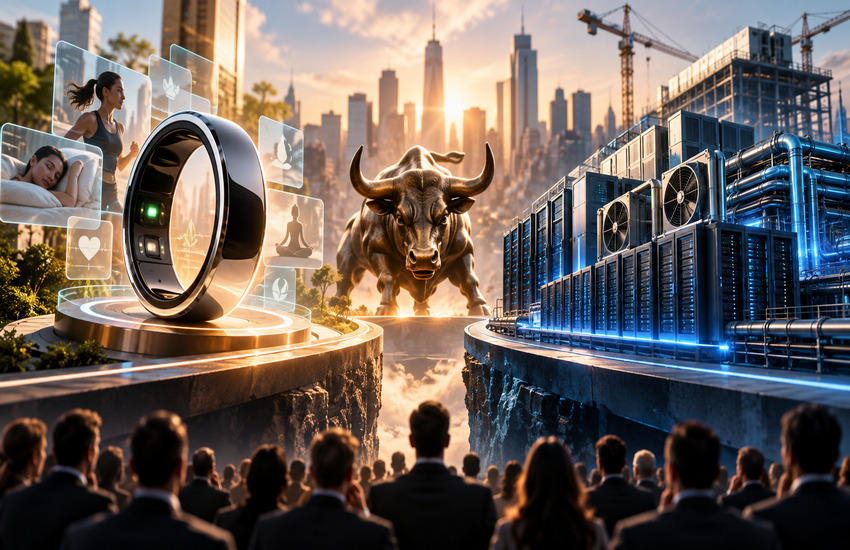
Wall Street is about to get an unusual experiment. Two fast-growing technology businesses are preparing to enter the public market at almost the same time, putting Upcoming Tech IPOs firmly in focus. Yet they represent two very different ways to invest in the technology economy.
One is built around consumers, personal health data, hardware, and recurring subscriptions. The other sits much deeper in the technology stack. It supplies the physical infrastructure needed to keep the data-center boom moving.
That contrast matters because the IPO market is facing a demanding backdrop. Investors have become more selective as bond yields, interest-rate uncertainty, and questions around technology valuations remain in focus. Reuters has described the coming listings as important tests of investor demand.
So this is about more than two new stocks. The market is about to put two very different growth stories, financial models, and valuation cases under the microscope.
Consumer Health & Subscription Growth Come To Upcoming Tech IPOs
The first side of the showdown is Oura. The smart-ring company plans to sell 50 million shares at an indicated price of $40 to $44. At the top of that range, the offering could raise about $2.2 billion and give Oura a fully diluted valuation of roughly $15.62 billion.
The growth behind that valuation is substantial. Revenue reached $1.21 billion during the nine months through June 2026, up 74% year over year. Net income increased from $1.6 million to $60.8 million. Gross margin also improved from 51% to 55%.
But the most interesting part may be Oura’s subscription engine. Paid members doubled to 5 million, while 12-month weighted-average retention stood at roughly 85%. Oura expects around 5.7 million paid members by fiscal year-end. That growth gives Oura a distinctive position among Upcoming Tech IPOs.
Membership revenue represented 20% of revenue during the latest nine-month period. More importantly, that business carried an 89% gross margin. Hardware still generates most revenue, but subscriptions add a recurring component that traditional consumer-device businesses often lack.
That mix will be central to how investors assess Oura’s proposed valuation.
AI Infrastructure Offers A Very Different Bet On The Boom
Across the ring is Accelevation Holdings, and the similarities largely stop at rapid growth. Accelevation isn’t selling a consumer product. It designs, manufactures, and installs infrastructure for mission-critical environments, including large data centers.
Its products cover areas such as power distribution, modular infrastructure, and thermal management. Its customers include hyperscale, colocation, AI, and cloud data-center operators. In other words, Accelevation is selling some of the physical equipment required to turn massive computing investments into functioning facilities.
The company plans to offer 30 million shares at $20 to $24 each. At the high end, the offering could raise about $720 million, with Accelevation targeting a valuation of as much as $5.37 billion.
Growth has been rapid. Revenue increased 147% from 2024 to 2025. The pace accelerated further during the first half of 2026. Revenue reached $437.5 million, up nearly 176% from $158.6 million a year earlier. That pace makes its listing particularly notable among Upcoming Tech IPOs.
Accelevation also reported approximately $1.1 billion of backlog as of June 30.
That figure gives investors some visibility into future activity. However, the company warns that backlog can be delayed, changed, or canceled. It therefore shouldn’t be treated as guaranteed future revenue.
These IPOs present two fundamentally different technology growth models: consumer hardware supported by recurring subscriptions versus infrastructure exposed to data-center investment. Both companies are expanding rapidly, but investors must weigh growth durability against valuation, revenue quality, and distinct demand risks.
Rapid revenue growth, improving economics, recurring membership revenue, and data-center backlog give investors two distinct mechanisms for sustaining technology-driven expansion.
High growth expectations leave both valuations dependent on durability as consumer demand and data-center capital spending face fundamentally different execution risks.
Watch whether Oura sustains membership growth and retention while Accelevation converts its approximately $1.1 billion backlog into realized revenue.
The IPO comparison ultimately tests what public investors are prepared to pay for two different forms of technology growth. Oura depends more heavily on consumer engagement and subscription economics, while Accelevation depends on continued data-center investment and execution against backlog.
Two Growth Engines Come With Two Very Different Risk Profiles
This is where the IPO showdown becomes particularly interesting. Oura and Accelevation are growing quickly for entirely different reasons, so investors have to evaluate very different risks.
Oura’s model depends heavily on consumers continuing to buy its rings. Hardware generated about 80% of revenue during the nine months through June. Memberships supplied the remaining 20%. The two businesses are closely connected because customers generally need the ring to use the paid membership service.
That puts product demand, retention, competition, and consumer spending near the center of Oura’s story. Its subscription business helps create recurring revenue, but hardware remains the primary gateway.
Accelevation faces another set of questions. Its growth is tied more directly to data-center construction and technology capital spending. That gives it exposure to AI infrastructure without requiring consumers to buy a device or subscription.
Its addressable market is also expanding rapidly. Accelevation’s filing cites an estimated $22 billion actionable data-center market in 2025. That market could approach $80 billion by 2030, representing an estimated 30% compound annual growth rate. This market exposure gives investors another angle to consider as they evaluate Upcoming Tech IPOs.
But data-center projects can move around. Construction schedules change, customer spending can slow, and backlog doesn’t automatically become revenue.
One IPO therefore tests consumer engagement. The other tests confidence in the physical AI buildout.
Selling Shareholders & Valuations Add Another Layer To The Showdown
There is one more detail investors shouldn’t overlook: a meaningful portion of both offerings involves existing shareholders selling stock.
Oura’s offering consists of 50 million shares, but the company itself is selling only 13.5 million. Existing shareholders are offering the other 36.5 million shares. Reuters also reports that Eli Lilly has indicated interest in buying up to $100 million of stock. Dragoneer-affiliated funds have indicated interest in purchasing up to $300 million. Those expressions of interest aren’t binding commitments.
Accelevation has a similar structure. Its IPO consists of 30 million shares. The company is offering roughly 8.6 million, while selling shareholders account for approximately 21.4 million shares.
The valuation gap is equally striking. Oura is seeking a fully diluted valuation of roughly $15.6 billion. Accelevation is targeting as much as $5.37 billion. The difference highlights the range of valuation cases investors face across Upcoming Tech IPOs.
Those figures aren’t directly comparable because the businesses have different margins, revenue mixes, capital needs, and growth drivers.
Still, they show what makes this IPO week unusual. Public investors will effectively be asked how much they are willing to pay for two completely different forms of technology growth.
The Market Must Decide Which Kind Of Growth Deserves The Premium.
Final Thoughts
Oura and Accelevation arrive with strong growth numbers, but the similarities end quickly. Oura combines consumer hardware with an increasingly important high-margin subscription business. Accelevation sells the infrastructure supporting the expansion of AI, cloud computing, and data centers.
Oura’s 74% nine-month revenue growth, 5 million paid members, improving profitability, and 89% membership gross margin help explain why the company is seeking a valuation above $15 billion. Accelevation brings faster recent revenue growth, a $1.1 billion backlog, and direct exposure to a data-center market that its filing expects to expand substantially through 2030.
The proposed valuations will therefore put different revenue multiples and assumptions about future growth in front of investors. Those multiples need to be considered alongside margins, recurring revenue, customer concentration, capital requirements, and execution risk.
That makes the coming IPOs an unusually clean comparison. Wall Street isn’t simply deciding whether it still wants technology IPOs. It is getting a chance to show what kind of technology growth it is currently willing to value most highly.
Disclaimer: We do not hold any positions in the above stock(s). Read our full disclaimer here.